
I wrote about why Wall Street is punishing Netflix and Macron’s big entertainment summit. I also write The Media Mix.
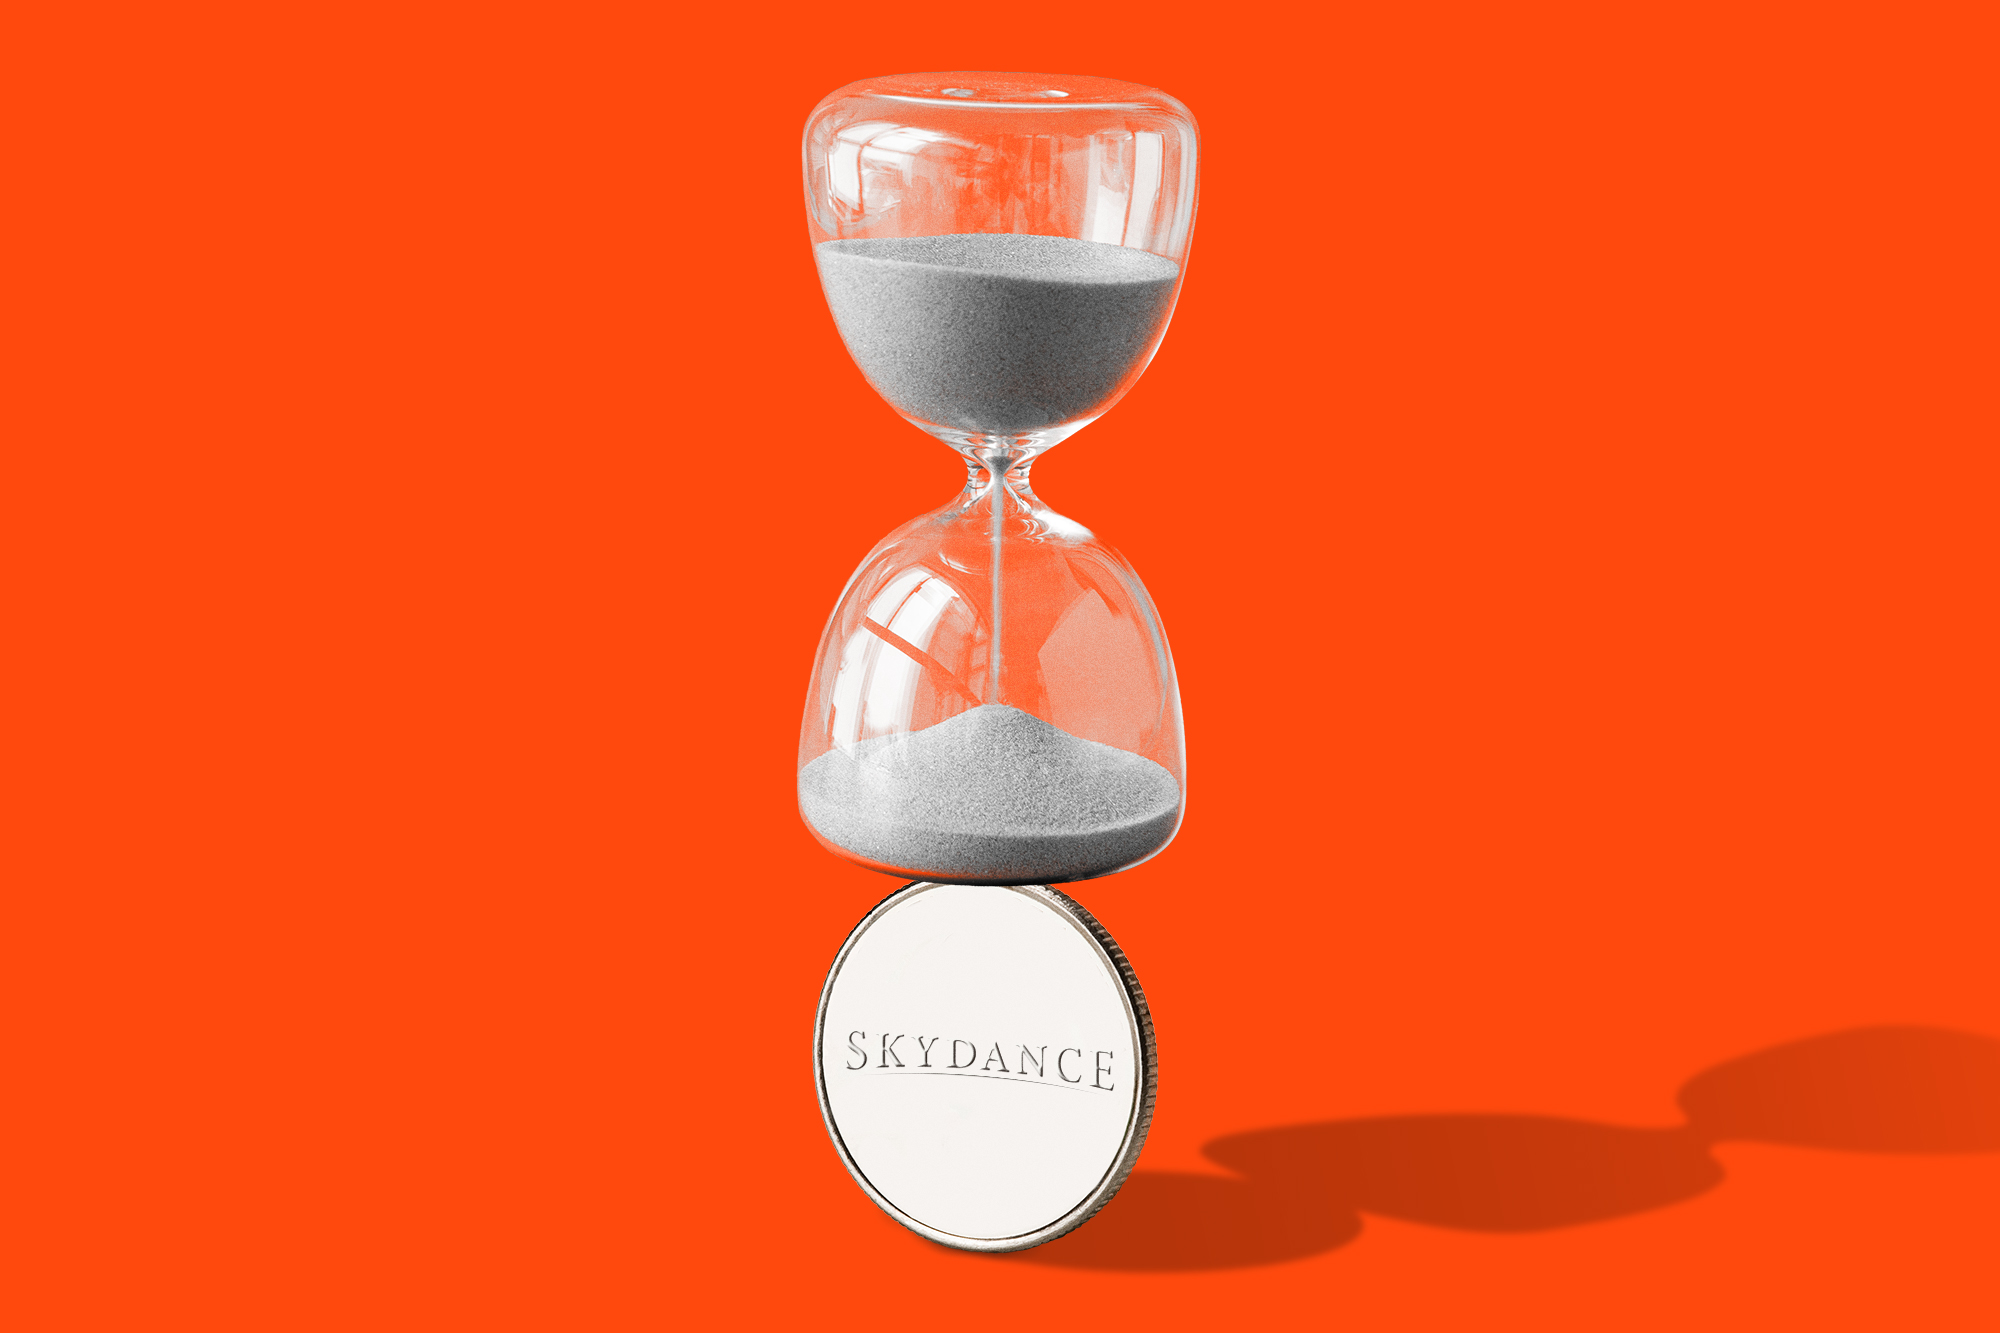
As far as Wall Street is concerned, Larry and David Ellison still have a long way to walk on a very thin rope, and this week may be the hardest stretch yet. The deal is set to close Tuesday, and once the Champagne and investor sizzle reels fade, the markets get their turn to speak.
Those with long memories will recall the hype around Warners’ assets in April 2022, when Discovery took charge. Investors who bought into that turnaround story watched their shares sit in neutral, with little place to go until the company announced a breakup. Skydance’s $110 billion takeover of Warner Bros. Discovery let the more patient of those investors get out intact. But the new company starts life with even more debt, even steeper declines in cable viewing and a slow-growth streaming market. This time around, investors could be in fool-me-twice mode.

“We worry that the melting iceberg of linear TV is stronger than the growth trajectory of streaming plus cost synergies,” senior Needham media analyst Laura Martin wrote in a note last week. The combined company has some positives: two storied studios, former Mattel chief Ynon Kreiz as co-CEO and billions in savings on the table. But with this much debt, investors won’t be patient for long.

That’s the bind. The debt sets a short clock, and the levers available to the Ellisons are either fast but limited or big but slow. Cost cuts can come quickly, but some of the most obvious targets are walled off by the consent decree reached last month with California and 11 other states that had sued to block the merger on antitrust grounds. Streaming is the only place left to grow, but the market has matured, and analysts don’t expect the deal to show traction until 2030. Paramount Skydance didn’t respond to requests for comment.
The verdict from much of Wall Street is brutal and pessimistic. One M&A expert says Skydance has “all the factors of what make a mega merger fail.” Another analyst warns that the company’s shrinking cable business is melting faster than streaming and cost cuts could ever compensate for.
Ahead: I talk to top analysts about the $80 billion debt load, the surprising areas where the cuts are likely to hit first, the bond deal that left investors nursing losses almost immediately, why Larry Ellison’s Oracle stake — and his own massive debt exposure — is suddenly part of the risk, the streaming math that may not work until 2030, and the Kreiz factor.
Don’t stop here
Get the rest of this story — and the scoops and intelligence Hollywood reads first.
Already a subscriber?
Comments
Only Ankler All Access subscribers can comment
Already a subscriber?