

I host the Ankler Agenda podcast and wrote about how Peter Rice will fit at Netflix after Bela Bajaria’s ouster and Skydance’s three-studio problem.
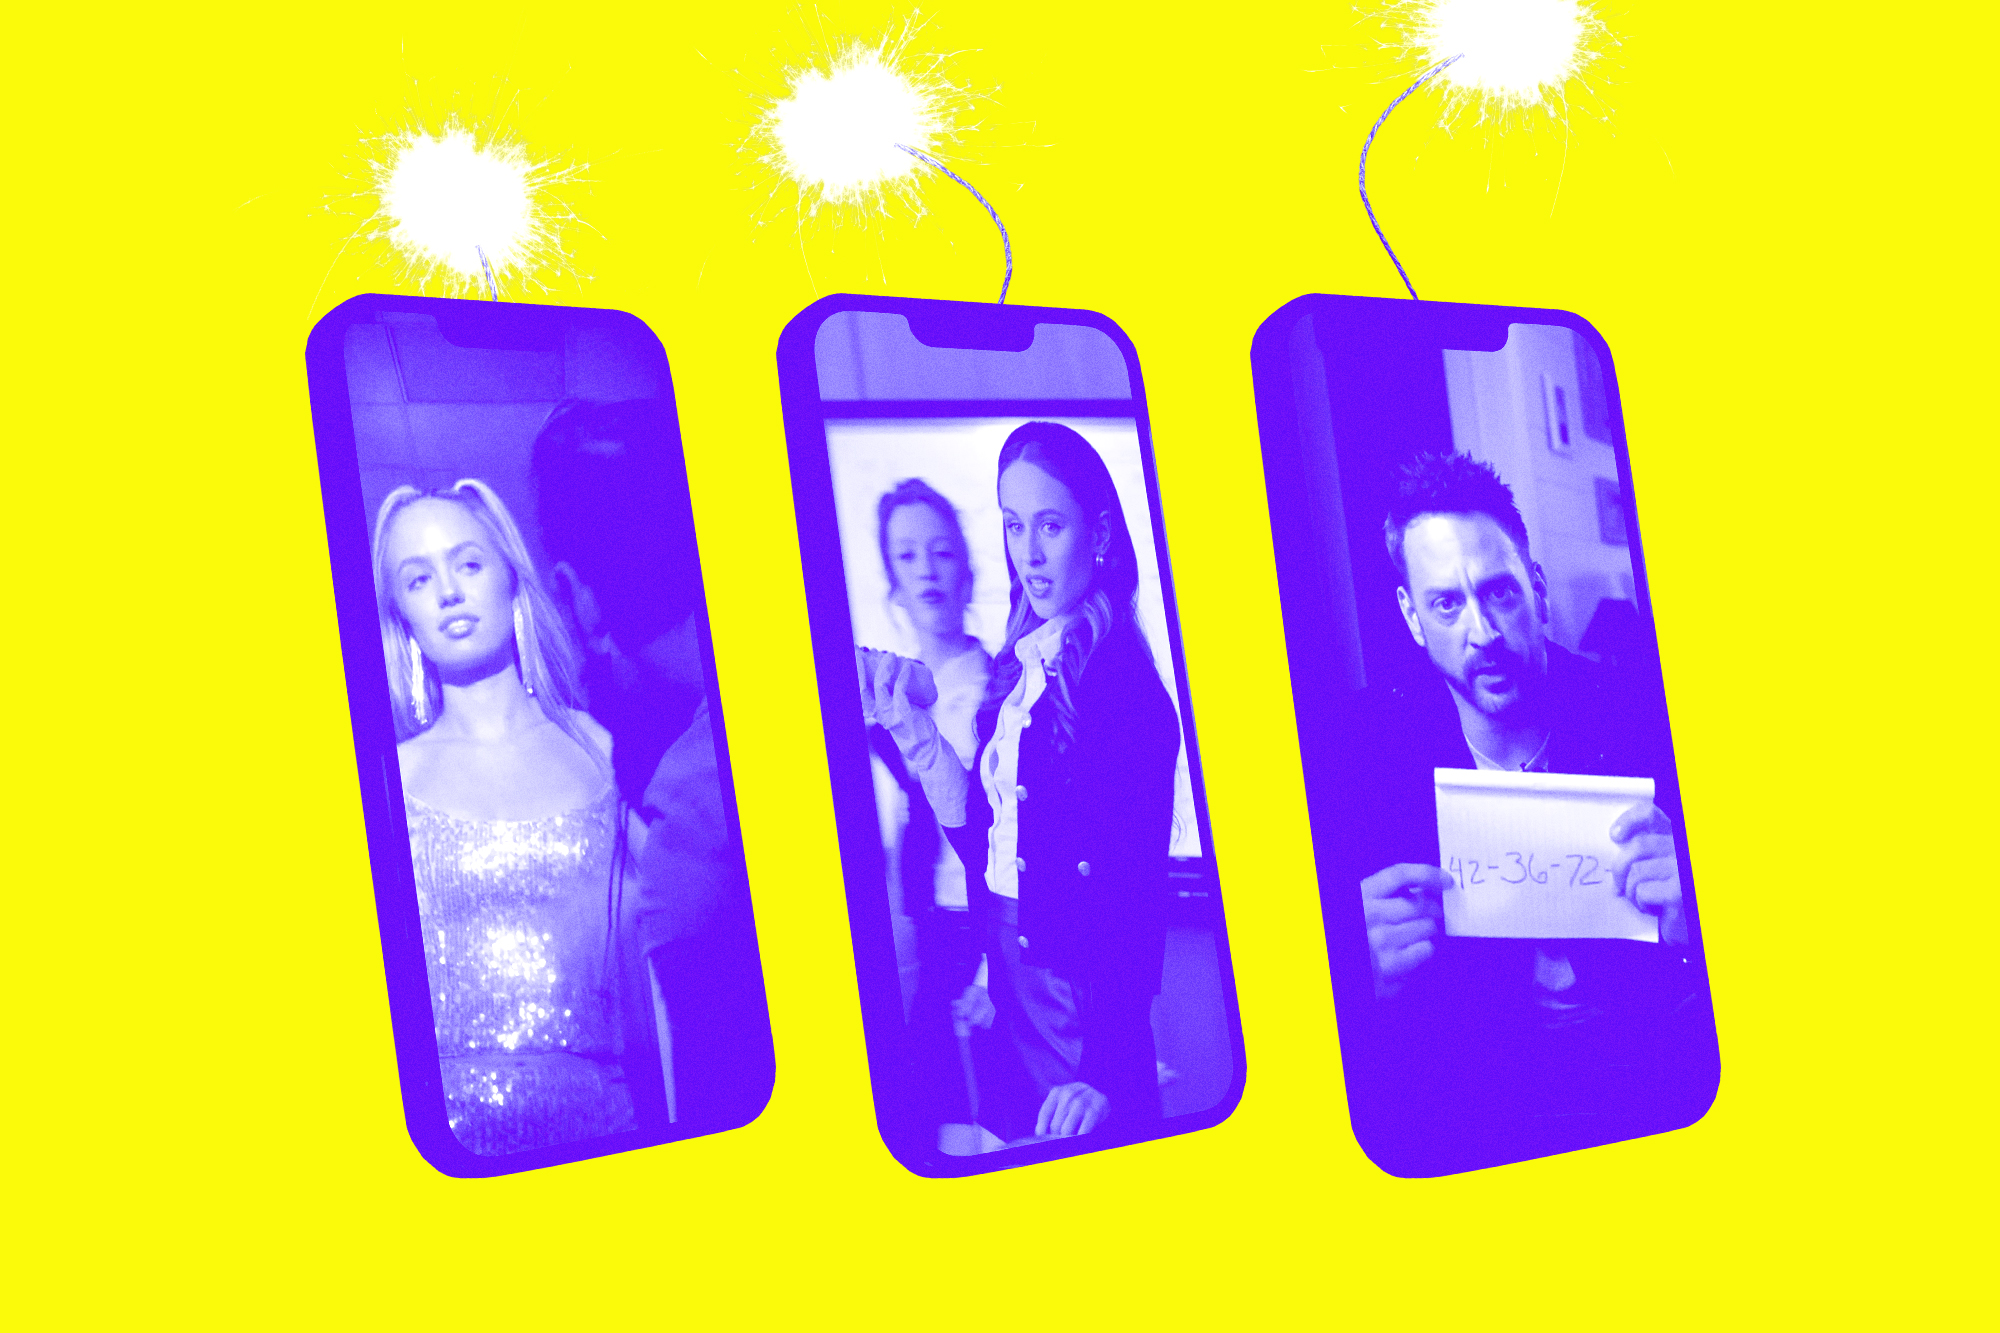
It feels like just one Quibi ago when microdramas were hailed as a savior to the sorry state of production in Los Angeles, giving out-of-work actors jobs and renting out soundstages otherwise hosting tumbleweeds.
Indeed, the gold rush has produced a staggering amount of content. In just three months, the 16 leading vertical video apps outside China released 32,000 titles — more than 10,000 new shows a month.
But even 32,000 shows aren’t enough to guarantee success — or to yield even one show that would qualify as a category-defining “hit” that has permeated the larger culture (and thus prove the model).
The competition for viewers in a short period of time has become so fierce that microdrama apps, with alluringly cheap production costs, are spending half or more of their revenue on an expense I’ll tell you about below (hint: It has nothing to do with the actual shows). Some apps already are calling it quits. VeYou, launched earlier this year by Top Gun: Maverick producer Tommy Harper, is shutting down its standalone app on Nov. 6.
And looming over the entire business is — what else — AI. In China, where the phenomenon began, a whopping 91 percent of all microdrama releases in the third quarter were AI-generated, according to data from Owl & Co., the consulting firm led by Fox alum and Wondery founder Hernan Lopez. That’s a harbinger of what’s to come stateside, which trails about 18 to 24 months behind China on this format.
So is the microdrama gold rush already headed for a shakeout? Or, as Lopez believes, is the industry still one enormous hit away from changing everything?
The answer may depend on whether these companies can get one surprisingly expensive part of their business under control — before they run out of money trying.
Plus: I have a must-see list on the top-performing genres in verticals and no, it’s not all werewolves…
Don’t stop here
Get the rest of this story — and the scoops and intelligence Hollywood reads first.
Already a subscriber?
Comments
Thanks Elaine. I think the customer acquisition numbers are the real story here, and they point at something the piece folds together. Apps spending half their revenue to buy users is a business model problem. 32,000 titles in a quarter without one show anybody outside the apps can name is a craft problem. Vertical is a medium. Microdrama is a business model. They are not the same thing, and the article uses “format,” “genre” and “industry” interchangeably for both.
Hernan says the breakout arrives when a platform puts marketing muscle behind an original. Marketing muscle has never made a film great. Lawrence of Arabia didn’t owe anything to Columbia’s theatrical footprint in 1962. Lean, Bolt, Freddie Young and O’Toole understood what 70mm could do that no frame before it could, and they wrote and shot for that. House of Cards worked because Fincher and Willimon made something worth staying up for; Netflix’s contribution was letting people stay up.
The same holds in 9:16. The vertical frame has its own grammar for composition, blocking, performance and editing, and almost nobody producing at factory volume is using it. Ten thousand shows a month, 91 percent AI generated in China, is instinct without grammar at industrial scale. The first real vertical hit will come from someone who treats the phone the way Lean treated the 70mm frame. Xian Le’s Sundance lens is the closest thing in your piece to that, and I’d bet on it before I’d bet on any app’s ad budget.
Great comments. The universal solution to high customer acquisition costs- with any product, in any market- has always been to make a better product. And, of course, if you’re buying all your customers, there is zero barrier to entry for your competitor (they can buy the same customers you can). Nobody has even mentioned the cost of KEEPING those customers, when everything looks the same. Churn is already Netflix’s biggest challenge. Verticals will be a brain-dead business model until they can deliver a product worth watching.
Only Ankler All Access subscribers can comment
Already a subscriber?